Later Life Lending
Later life lending brings together a range of mortgage and borrowing solutions designed specifically for homeowners aged 55 and over.

Helping You Make The Most Of Your Home In Later Life
If you’re aged 55 or over, your home may be one of your most valuable assets. Whether you’re looking to boost your retirement income, help family members financially, pay off an existing mortgage or simply enjoy greater financial freedom, there are a range of later life lending options that could help.
At Fluent Money, we specialise in helping homeowners understand these options. We’ll explain how each solution works, answer your questions and help you find an approach that’s right for your circumstances, both now and in the future.
What Is Later Life Lending?
Later life lending brings together a range of mortgage and borrowing solutions designed specifically for homeowners aged 55 and over.
Rather than taking a one-size-fits-all approach, these products are designed to reflect the changing financial priorities many people experience later in life.
You may be looking to:
- Access money tied up in your home
- Supplement your retirement income
- Pay off an existing mortgage
- Fund home improvements or adaptations
- Help children or grandchildren financially
- Enjoy greater financial flexibility in retirement
The most suitable solution will depend on your circumstances, goals and whether you’re comfortable making monthly repayments.
Not Sure If Equity Release Is Right For You?
Equity Release isn’t the only later life lending solution available.
If you have a reliable retirement income and are comfortable making monthly payments, a Retirement Interest Only (RIO) Mortgage could be an alternative worth exploring.
Our advisers will take the time to understand your circumstances, explain the available options and help you compare the solutions that may suit your needs.
Understanding Your Later Life Lending Options
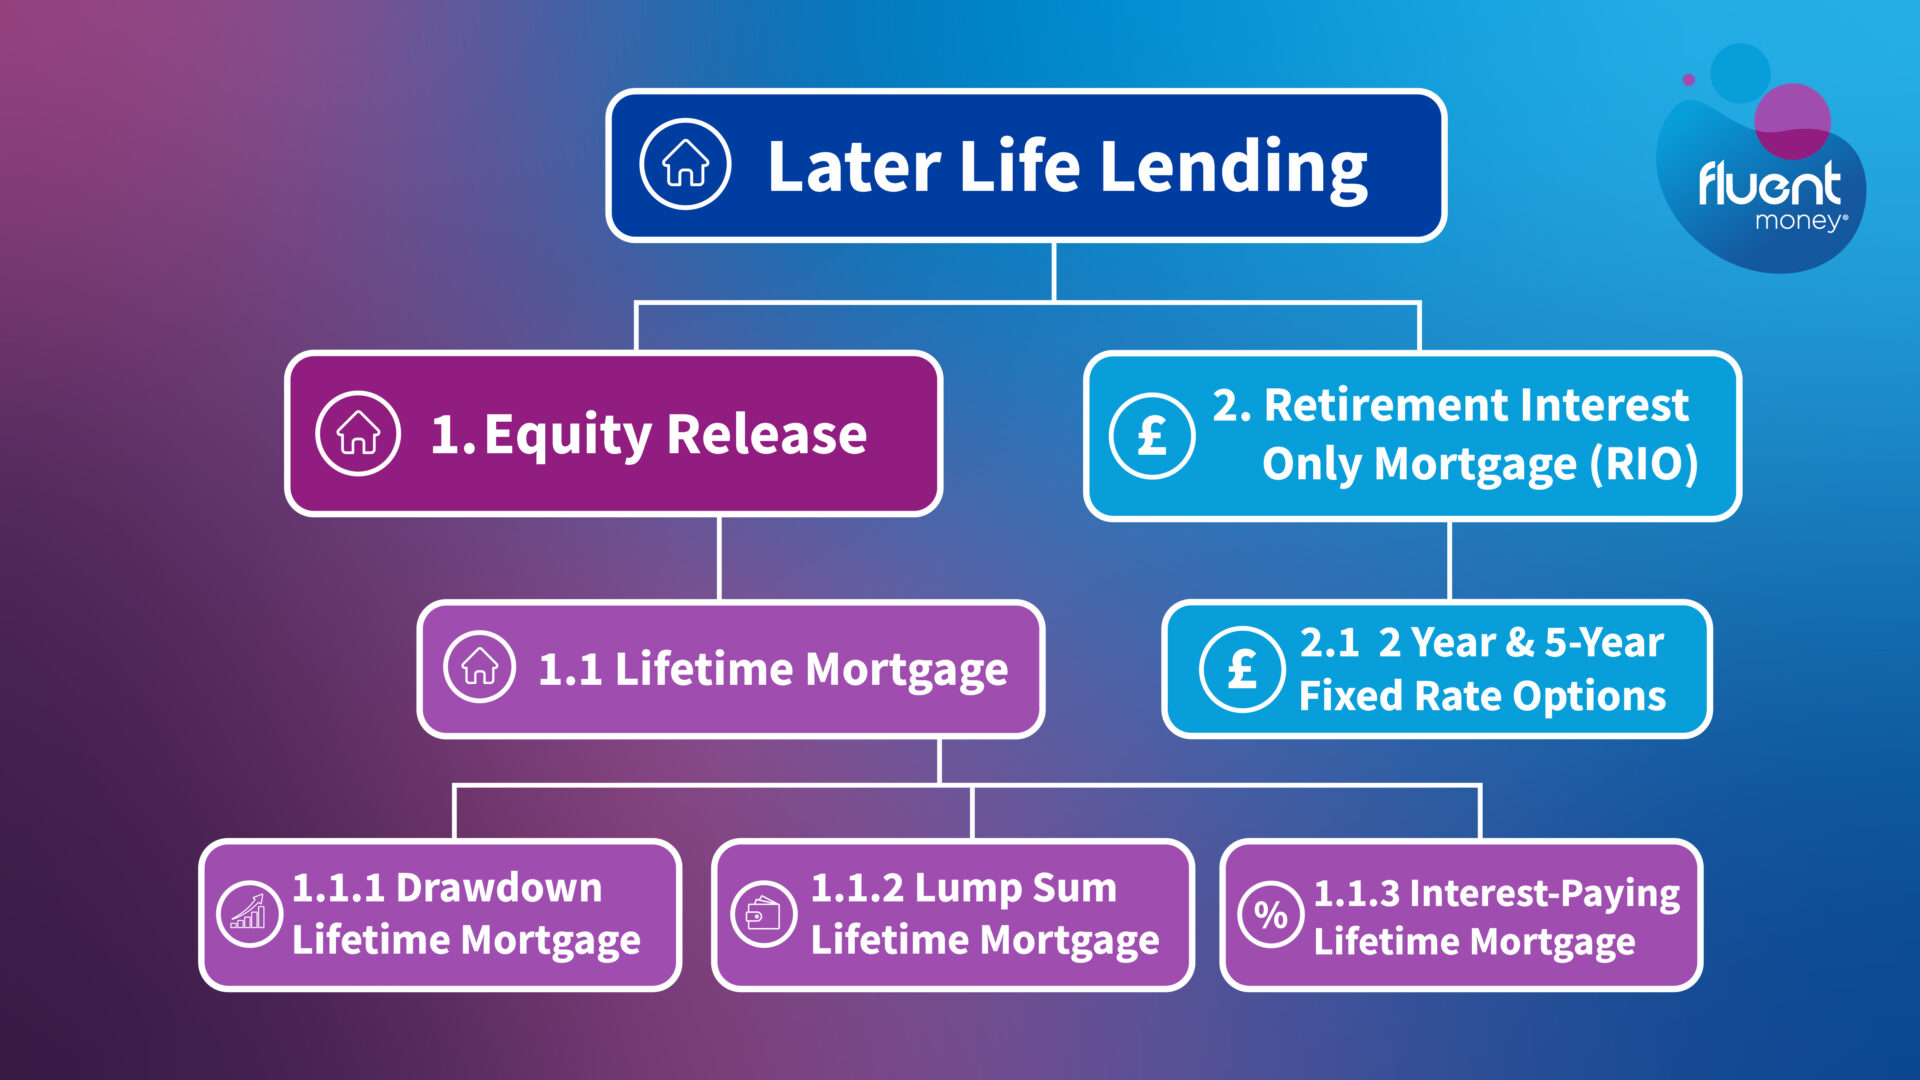
Later life lending is an umbrella term that covers a range of borrowing solutions designed for homeowners aged 55 and over. As shown below, there are two main routes: Equity Release and Retirement Interest Only (RIO) Mortgages. Equity Release includes Lifetime Mortgages, which can be arranged as a Drawdown, Lump Sum, or Interest-Paying Lifetime Mortgage, depending on how you want to access and manage your borrowing. The diagram below shows how these options fit together and where each solution sits within the wider later life lending market.
Our Later Life Lending Solutions

Equity Release
Equity Release allows eligible homeowners to unlock some of the value tied up in their property while continuing to live there.
Many plans don’t require mandatory monthly repayments, making Equity Release a popular option for people looking to access tax-free cash in retirement.
Lifetime Mortgages
A Lifetime Mortgage is the most common type of Equity Release and the main later life lending solution offered by Fluent Money.
It allows you to borrow against your property’s value while retaining ownership of your home. Depending on the product, you may be able to take a lump sum, access funds through a drawdown facility or make optional repayments to help reduce interest over time.
Retirement Interest Only Mortgages
A Retirement Interest Only (RIO) Mortgage is an alternative for homeowners who have sufficient retirement income and are comfortable making monthly interest payments.
Because the interest is paid each month, the amount borrowed remains the same, which may help preserve more equity in your property.
Which Option Sounds Most Like You?
Access Money Without Monthly Repayments
A Lifetime Mortgage or another form of Equity Release may be worth exploring.
Need Some Money Now And More Later
A Drawdown Lifetime Mortgage could provide the flexibility to access funds as you need them, with interest only charged on the money you’ve withdrawn.
I Can Afford Monthly Payments
A Retirement Interest Only Mortgage may help you access money from your property while keeping the loan balance level.
I’m Not Sure Which Option Is Right
That’s exactly what we’re here for. Our advisers will explain your options clearly and help you compare the solutions that may suit your circumstances.
Our advisers can explain your options clearly and answer any questions you may have.
Important information
You should always think carefully before securing a loan against your property.
A lifetime mortgage will reduce the value of your estate and may affect your entitlement to means-tested benefits. Clearing an existing mortgage with a lifetime mortgage may result in higher cost of borrowing. Mortgage Advice Bureau charges a fee for later life mortgage advice. The fee is up to £1,295